Executive Overview
Personal finance apps face a trust barrier that no other vertical shares: the product asks for access to the viewer’s most sensitive data before it has earned a single moment of credibility. The TikTok UGC format that solves this is not feature demonstration but shame-to-relief scripting—content that opens with the specific financial moment the viewer is quietly terrified of, names it without judgment, and then shows the mechanical relief that follows. The mechanism is validated by the category’s conversion architecture: personal finance hooks that name a costly moment or a familiar mistake outperform topic-label openers by margins that separate converting creative from invisible creative . The stakes are also higher than in any other vertical: financial services are a restricted category on TikTok, requiring 18+ targeting, regulatory licensing, and approval through a sales representative, and debt relief services are explicitly prohibited in most markets . The format works. The compliance boundary is not optional.
Theoretical Basis and Psychology of Mechanics
The debt payoff and budgeting relief format operates on a psychological foundation that inverts the standard finance advertising arc. Most finance app marketing sells control: the dashboard, the category breakdown, the feeling of being on top of things. The shame-to-relief script sells the end of a specific anxiety: the stomach drop before payday, the balance that has not moved in a year, the minimum payment that feels like a treadmill. Control is aspirational. Relief is urgent, and urgency converts.
The first mechanism is the shame acknowledgment as trust signal. Money anxiety is universal, and almost nobody feels like they have the full picture . The viewer scrolling past finance content is not looking for another person who has it together. They are looking for evidence that someone else has been where they are. The hook that works is not “here is how to budget” but “I checked my bank account the day before payday and felt my stomach drop” . The shame is named, not solved, in the first three seconds. The relief comes later. The sequence is the mechanism.
The second mechanism is the minimum payment trap as shared enemy. The data is brutal and widely unrecognized: 34% of Americans with debt say their balance has not budged despite making payments, and 13% of cardholders are in persistent debt where a full year of payments went more toward interest than principal . The minimum payment is not a payoff plan, and the script that says so out loud gives the viewer permission to feel angry at a system rather than ashamed of themselves . The app enters not as a judge but as the tool that makes the math visible. The enemy is the interest, not the viewer.
The third mechanism is the honest timeline as credibility architecture. Finance audiences have been burned by “get rich quick” promises and “debt-free in 90 days” claims. The relief script must name a realistic, specific timeline—not a guarantee, but a projection. “At this rate, I will be done in fourteen months instead of three years” is credible because it is computable and not miraculous. The app’s value is the visibility of the path, not the speed of the arrival. This distinction is both the trust mechanism and the compliance boundary: TikTok prohibits offers of quick wealth acquisition and financial products that are too good to be true .
The fourth mechanism is the restricted-category compliance floor. Financial services branded content on TikTok requires explicit permission, a Registered Business Account, and partnership through TikTok One, and the content is age-restricted to 18+ . Debt relief programs and debt consolidation services are prohibited in many markets, and the creative cannot imply guaranteed approval or instant resolution . The script sells the visibility of the problem and the mechanics of the plan, never the guarantee of the outcome. The app is a flashlight, not a rescue helicopter.
Step-by-Step Algorithm & Methodology
The framework below sequences a debt payoff and budgeting relief UGC asset from cold open to download, with each phase engineered to convert shame into relief while staying inside the financial services compliance boundary.
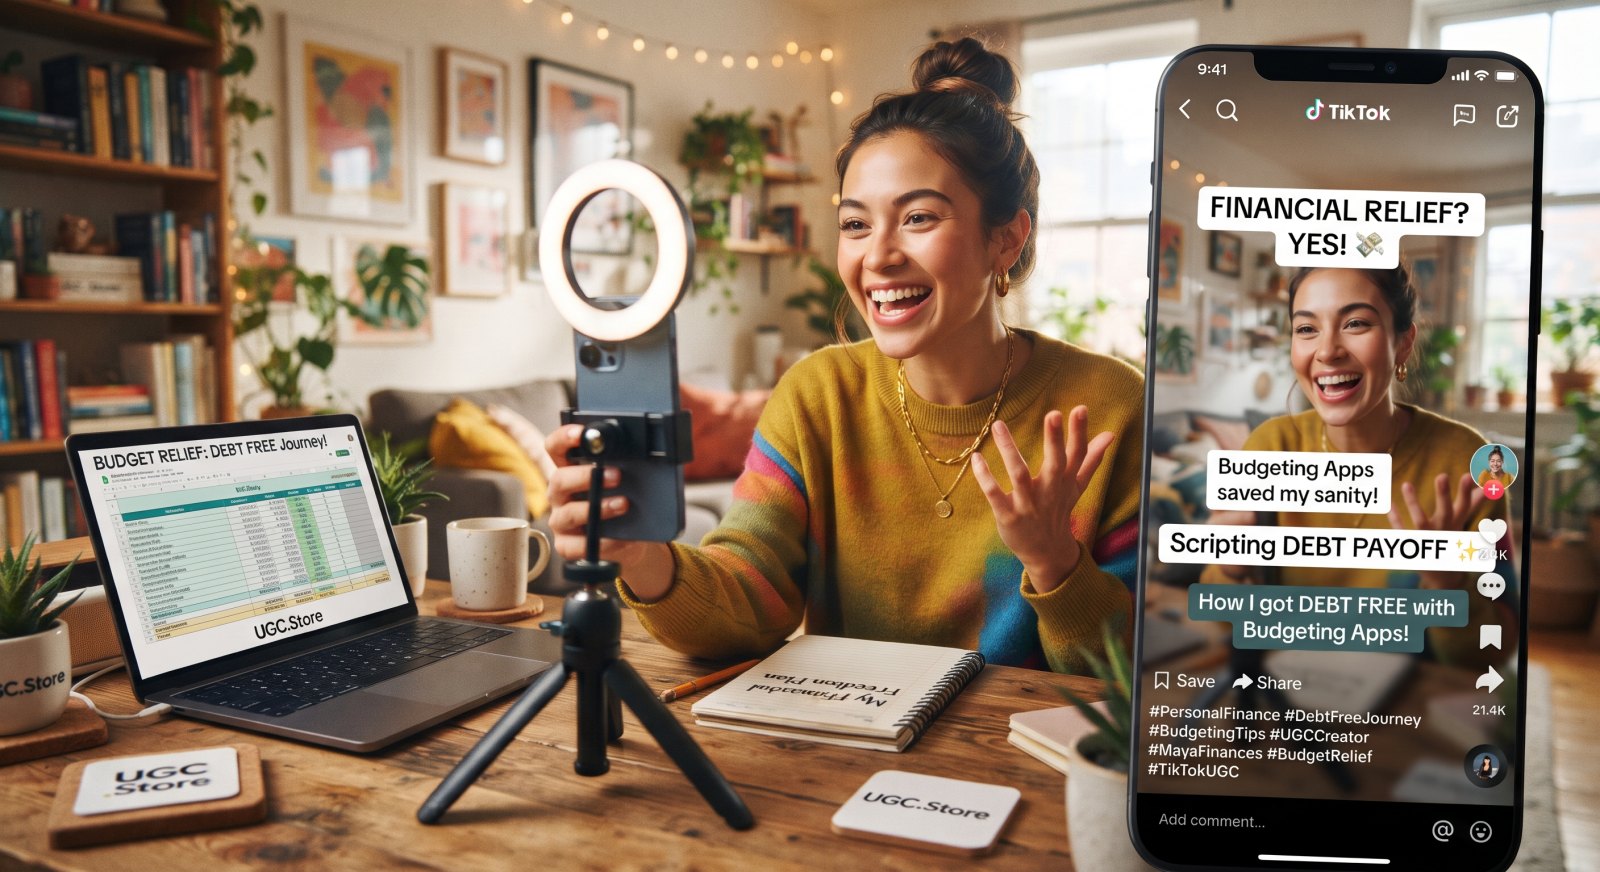
Phase 1 — The Shame Moment Cold Open (0–3 seconds). The creator opens mid-moment, not mid-explanation. The first line names a specific, recognizable financial anxiety with no setup and no greeting: “I checked my credit card balance and it was the same number it was six months ago.” or “My paycheck hits and it is gone by the fifteenth and I do not know where it went.” The opening frame is the creator’s face, expression carrying the specific weight of the memory—not crying, not dramatic, just tired recognition. The viewer must see their own financial moment in the creator’s face before they know what the video is selling. The hook is not a topic. It is a mirror .
Phase 2 — The Specific Math (3–10 seconds). The creator names one number that makes the problem legible. “I owe $7,200. I have been paying $180 a month for a year. My balance went down by $340.” The number must be true or truthfully representative and it must show the minimum payment trap without explaining it abstractly. The screen can show a statement or a banking app with the balance visible—no names, no account numbers, just the number that tells the story. The viewer who has watched their own balance stagnate recognizes the math immediately. The viewer who has not is now afraid that they are in the same trap.
Phase 3 — The App as Visibility Tool (10–18 seconds). The app enters not as the solution but as the thing that made the trap visible. The creator shows the app’s debt payoff screen—the balance, the interest breakdown, the projected timeline—and names what changed: “This is the first time I have seen where the money is actually going. The interest is $118 a month. I have been paying $180 and $118 of it is just—gone.” The screen recording is the demo, and the demo’s value is legibility, not magic. The app does not pay the debt. It shows the debt, which is the first step to paying it .
Phase 4 — The Honest Friction Note (18–25 seconds). The creator names what the app cannot do and what the process actually requires. “The app does not pay the debt for you. You still have to find the extra money. For me that meant cancelling three subscriptions and not ordering takeout on Fridays. It is not fun. It is just math.” This phase is the format’s trust engine and its compliance mechanism simultaneously. It acknowledges that the product is a tool, not a transformation. The viewer who has been burned by “debt-free in 90 days” promises is disarmed by a creator who says “this will take a while and it will require choices” .
Phase 5 — The Relief Frame (25–32 seconds). The creator shows the projected timeline and the feeling of seeing the end. “When I put in the extra $200, the date moved from 2029 to 2027. I am not debt-free. I am not close. But I can see the date now, and that is the first time I have been able to see it.” The relief is not the elimination of the debt. It is the visibility of the exit. The screen shows the timeline shifting, and the creator’s face shows the specific relief of someone who has been driving without a map and has just been handed one.
Phase 6 — The Shared Math CTA (final 5–7 seconds). The creator closes with a question that invites the viewer’s own number into the comments. “Tell me the number you have been afraid to look at. Not the balance—the number of months. How long until it is gone? I will go first: twenty-six months. Your turn.” The CTA does not ask for downloads. It asks for confessions, and the confessions are the conversion mechanism. The comment section becomes a shared math archive, and the viewer who reads ten timelines before downloading is already inside the app’s social context.
Ready-to-Use Working Templates & Scripts
Script One: “The Number That Did Not Move” (Format: debt payoff UGC, 38 seconds).
Opening frame: creator’s face in close-up, kitchen table lighting, expression of quiet exhaustion. Hook text: “my balance was the same number for six months”. Dialogue: “I have been paying $180 a month on this card for a year. I checked the balance last week and it went down by $340. Three hundred and forty dollars. For a year of payments.” Screen: banking app statement, balance visible, no account numbers. “I did the math in my head and I realized most of what I was paying was interest. The minimum payment was not a payoff plan. It was a subscription to staying in debt.” App reveal: screen recording of a debt payoff calculator, the interest breakdown visible. “This is the first time I have seen the split. $118 goes to interest. $62 goes to the balance. I have been paying $180 and $118 of it was just—gone.” Honest friction: face to camera, screen dimmed. “The app does not fix this. I still had to find the extra money. I cancelled three subscriptions and stopped ordering takeout on Fridays. It is not fun. It is just math.” Relief frame: screen shows the projected payoff date shifting from 2029 to 2027. “When I put in the extra $200, the date moved two years. I am not debt-free. But I can see the date now.” CTA: face direct to camera. “Tell me the number of months until your debt is gone. Not the balance. The months. I will go first: twenty-six. Your turn.”
Script Two: “The Fifteenth” (Format: budgeting relief UGC, 34 seconds).
Opening frame: creator’s face, phone in hand, slight laugh of disbelief. Hook text: “my money disappears by the fifteenth and i finally know why”. Dialogue: “I used to think I was bad with money. Like, fundamentally bad. Then I actually looked at where it was going and it was not random. It was the same four things every month, and I had no idea because I was scared to look.” Screen: budgeting app category breakdown, four categories highlighted. “Subscriptions I forgot about. Groceries that were actually takeout. A gym I went to twice. And the ‘miscellaneous’ category, which is where my budget went to die.” App reveal: screen shows the app’s spending breakdown, the categories clear and legible. “This is the first time I have seen it laid out. I am not bad with money. I am just someone who never looked. Those are different things.” Honest friction: face to camera. “The app does not stop me from ordering takeout. It just shows me that I did. The stopping is still on me.” Relief frame: screen shows the budget with a small surplus. “I found $140 a month I did not know I had. It is not a new car. It is a start.” CTA: “What is the category that quietly eats your paycheck? I need to know I am not the only one with a miscellaneous problem.”
Script Three: “The Minimum Payment Trap” (Format: debt education UGC, 40 seconds).
Opening frame: creator’s face, direct to camera, serious but not dramatic. Hook text: “the minimum payment is not a payoff plan”. Dialogue: “Nobody tells you this when you get your first credit card. The minimum payment is designed to keep you paying. That is the business model. If you pay the minimum, you are not paying off the debt. You are renting it.” Screen: a simple payoff calculator showing a $7,000 balance at 22% interest with minimum payments. “At minimum payments, this balance takes twenty-six years to pay off. Twenty-six years. And you pay fifteen thousand dollars in interest on a seven thousand dollar balance.” App reveal: screen shows the app’s debt payoff planner, the avalanche and snowball options visible. “This is what I use to see the actual math. The app does not pay the debt. It shows you the trap, and then it shows you what happens if you add an extra fifty dollars a month. The difference is years.” Honest friction: face to camera. “I am not going to pretend this is easy. The extra fifty dollars has to come from somewhere. For me it came from a subscription I forgot I had and a coffee habit I am not proud of.” Relief frame: screen shows the payoff date shifting. “I am still in debt. But I am not renting it anymore. I am paying it.” CTA: “If you have ever paid the minimum and wondered why nothing changes, you are not alone. Tell me the number you have been avoiding. We will look at it together.”
Comparative Analysis Matrix
| Parameter | Feature-Demo Finance UGC | Shame-to-Relief Finance UGC |
|---|---|---|
| Core emotional mechanism | Aspiration and control | Recognition and the end of specific anxiety |
| Primary visual | Dashboard, category charts, settings | Creator’s face in the moment of financial recognition |
| Hook structure | “Here is how this app tracks spending” | “My balance was the same number for six months” |
| Viewer response | “That looks useful” | “That is literally me” |
| Comment behavior | “Does it sync with my bank” | Shared debt numbers, payoff timelines, confessions |
| Compliance exposure | Low but trust-poor | Manageable with honest timeline and no guarantees |
| Trust architecture | Feature-based; dependent on perceived accuracy | Recognition-based; dependent on specific shame naming |
| Friction Point | Feature-Demo Failure Mode | Shame-to-Relief Solution |
|---|---|---|
| Data privacy fear | App asks for bank access before earning trust | Creator names the fear and shows the app’s value first |
| Shame avoidance | Viewer does not want to look at their numbers | Creator looks first and survives the looking |
| Skepticism of promises | “Debt-free in 90 days” triggers scam detection | Honest timeline names months, not miracles |
| Minimum payment ignorance | Viewer does not know they are trapped | Specific math makes the trap visible and shared |
| Install intent | Driven by curiosity, fragile after setup friction | Driven by relief, durable through the math |
| Performance Metric | Category Benchmark (Finance UGC) | Shame-to-Relief Target |
|---|---|---|
| Hook rate (3-second) | 50–60% on cold traffic | Above 65% via specific shame moment |
| Hold rate (15-second) | 30–40% | Above 50% via math escalation |
| Comment rate | 0.5–1% of views | 2–4% via shared number CTA |
| CPI versus category | At benchmark | Below benchmark via Spark amplification |
| Day-7 retention signal | Weak; install driven by curiosity | Stronger; install driven by math they want to see |
Real-World Case Study Breakdown
A debt payoff app launched on TikTok in early 2026 with a creative library built entirely on feature tours: the debt snowball calculator, the interest breakdown screen, the projected payoff date. The production was clean and the math was accurate, but performance was diagnostic of the category’s trust barrier: CPI settled at $5.20** against a benchmark of **$3.50–$4.50 for finance apps on TikTok, with 15-second hold rate at 26% and comment sections that were either empty or suspicious (“is this legit,” “how do I know you are not selling my data”). The features were real and completely untrusted.
The strategic pivot abandoned feature demonstration entirely and rebuilt the creative around shame-to-relief scripting. The team recruited seven creators with follower counts between 10,000 and 45,000, selected for one criterion: their comment sections were full of people sharing their own financial numbers. The brief contained a single rule: “Open with the number you were afraid to look at. Do not solve it in the first five seconds. Let the viewer sit in the recognition before you show the app.”
The winning asset came from a creator with 18,000 followers whose opening line was: “I have been paying $180 a month on this card for a year and the balance went down by $340.” The video showed her actual statement, her actual confusion, and her actual realization about the interest split. The app entered at the ten-second mark, not as the solution but as the thing that made the trap visible. The honest friction note was: “The app does not pay the debt. I cancelled three subscriptions and I am not ordering takeout on Fridays anymore. It is not fun.” The relief frame showed the payoff date shifting from 2029 to 2027, and her face carried the specific relief of someone who could finally see the exit.
The video ran for seven weeks as organic and Spark-boosted content, generated 780,000 views, and drove 3,200 attributed installs at a blended CPI of $3.40—35% below the feature-tour baseline. The comment section filled with viewers posting their own months-until-payoff numbers, and the creator pinned one with the reply: “twenty-six months for me too. we are going to get there.” The governing insight: the app had been selling a calculator, when the buyer needed to see someone survive looking at the number .
Real-World Engineering & Creative Feedback
“The shame moment is the hook. Not the solution, not the feature, not the dashboard. The moment the creator says ‘I was afraid to look at this’ is the moment the viewer stops scrolling because they have been afraid to look too. The app is the reward for surviving the looking. That is the sequence. Get it backwards and you are selling a calculator to someone who is not ready to do math yet.” — Tasha Moreau, Finance UGC Creator, 42K followers
“We killed every ‘debt-free in X months’ hook from our creative library after the compliance review. Not because they did not convert—they did—but because the exposure was insane. TikTok prohibits financial offers that are too good to be true, and debt relief programs are outright banned in most markets . The replacement was honest timelines: ‘twenty-six months at this rate, twenty-two if I add fifty dollars.’ Same psychological mechanism, no guarantee. The CPI difference was within noise. The account survival was not.” — Ben Achterberg, Head of User Acquisition, Cartwheel Finance
“The minimum payment trap is the most underused education asset in finance UGC. Most people do not know that their minimum payment is not paying off their debt. They think they are making progress. The creator who says ‘your balance has not moved because you are renting the debt’ is doing the viewer a favor and earning trust at the same time. The app becomes the tool that shows the math they were never taught.” — Priya Deshmukh, Creative Strategy Lead, Pixel & Pulse Agency
“Spark Ads are mandatory for this format. A debt confession on a brand account reads as a desperate attempt to be relatable. The same confession on a creator’s account, with their real followers commenting ‘twenty-six months for me too,’ reads as a community math archive. The 27% CPI reduction from Spark is real, but the format-specific lift is bigger because the shame needs a social context to convert. Shame in a vacuum is just shame. Shame in a comment section is solidarity .” — Marcus Lehto, Performance Marketing Director, Northline Interactive
“We almost cancelled the shame brief because the first batch of creators made the videos too sad. They were opening with crying and despair and the comments were sympathetic but nobody was downloading. We rewrote the brief: ‘name the number, do not perform the pain. The viewer is not looking for a tragedy. They are looking for someone who looked at the number and survived.’ The difference in output was immediate. The tone shifted from despair to resolve. The CPI dropped by a third. The lesson: the shame is the hook. The relief is the conversion. You cannot sell relief from inside a tragedy.” — Elena Vasquez, Brand Director, Mosaic Finance
Production Self-Check Checklist
Shame-first hook verified — the opening three seconds name a specific, recognizable financial anxiety with no greeting, no app name, and no generic finance-tip language .
Number specificity confirmed — the creator names one concrete number (balance, payment, months, interest split) that makes the trap legible; the number is true or truthfully representative.
App enters as visibility tool, not savior — the screen recording shows the app making the problem legible, not the app solving the problem automatically.
Honest friction note delivered — the creator names what the app cannot do and what the process actually requires, spoken to camera with a shift in emotional register.
Timeline is specific and non-guaranteed — the projected payoff date is named as a projection, not a guarantee; no “debt-free in X days” claims surviving the edit .
No prohibited debt relief framing — the script does not offer debt consolidation, debt settlement, or any service that TikTok classifies as a prohibited debt relief program .
Age compliance verified — the creator appears clearly over 18; financial services content is restricted to 18+ audiences on TikTok .
Data privacy addressed implicitly — the creator shows the app’s value before showing the bank connection step; the viewer’s data fear is acknowledged, not ignored .
CTA invites shared number, not download — the closing prompt asks for the viewer’s own months-until-payoff or category confession, generating comment-section solidarity.
Spark authorization and brand permission secured — financial services branded content requires TikTok approval, a Registered Business Account, and partnership through TikTok One before the creator posts .
Advanced FAQ
How does a brand script debt payoff without triggering TikTok’s prohibition on debt relief services?
The compliance boundary is service type, not topic. TikTok prohibits debt relief programs, debt consolidation services, and debt settlement offers as advertising categories in most markets . A budgeting or debt payoff planning tool is not a debt relief service. The script must never offer to negotiate, settle, or consolidate the viewer’s debt. It offers to show the math and project the timeline. The line that survives review is: “This app shows you what your minimum payment is actually doing. It does not pay the debt. It shows you the trap.” The app is a visibility product, not a resolution product. The distinction is legal, not creative, and the script must hold it in every sentence.
What is the correct way to handle the data privacy fear that dominates finance app comment sections?
Do not argue with the fear. Name it before the viewer does. The highest-converting finance scripts include a line where the creator acknowledges the hesitation: “I know. You are not giving a random app your bank login. I felt the same way. The first thing I did was look at what it actually accesses and what it does not.” The creator then shows the app’s privacy screen or explains the data connection in plain language. The fear is not a barrier to conversion; it is a required beat in the trust sequence. The viewer who sees their own hesitation reflected in the creator’s hesitation is more likely to trust the creator’s eventual decision. The brand does not need to solve data privacy in a thirty-second video. It needs to show that the creator took the fear seriously .
Should debt payoff UGC use before-and-after balance screenshots, and if so, how?
Use them, but de-emphasize the transformation. The before-and-after is proof of the math, not the emotional center. The shame-to-relief script shows the balance as the problem statement, and the projected date as the relief. A dramatic before-and-after balance drop triggers the same skepticism as a fitness transformation photo: “this is not real, this is not achievable, this is an ad.” The marginal, honest improvement is more credible: “I am not debt-free. I am twenty-six months out instead of thirty-eight. That is the whole win.” The before-and-after should occupy three seconds or less and carry a caveat on camera: “This took eight months of extra payments and I still have a long way to go.”
How does a brand brief finance UGC without accidentally writing a get-rich-quick script?
The destructive brief contains the words fast, easy, guaranteed, secret, hack, and debt-free in. The productive brief contains three product facts, one required honesty beat (the months-until-payoff projection with a caveat), one forbidden phrase list (“get rich,” “debt-free in,” “guaranteed,” “secret”), and total freedom over the creator’s shame moment, number, and confession. The test is simple: read the brief aloud in a normal conversational voice. If it sounds like something a financially stressed person would say to a friend at a kitchen table, it is compliant and converting. If it sounds like a late-night infomercial, it is a policy violation waiting for a reviewer. The finance audience detects the difference at scroll speed, and the detection is fatal to trust and to the ad account .
What is the right measurement stack beyond CPI for this format?
CPI alone will mislead because the shame-to-relief format attracts users who are already anxious and may install with expectations the app does not meet if the onboarding does not deliver the visibility the ad promised. The correct stack includes first-session debt-entry completion: do users acquired through this creative actually enter their balances and see their payoff projection in the first session? The format is working if the acquired user completes the math step that the ad dramatized. The secondary metric is day-14 return rate: do users come back to check the projection, update the balance, or adjust the extra payment? The relief mechanism is the visibility of the timeline, and the timeline is only valuable if the user returns to look at it. The third metric is comment number correlation: if the comment section is full of viewers posting their own months-until-payoff and the day-14 return is high, the funnel is functioning. If the comments are full of “I downloaded it and it asked for my bank login and I deleted it,” the onboarding failed the trust sequence the ad established .
Custom Contextual Conclusion
Personal finance apps have spent years selling control to people who feel completely out of control, and wondering why the downloads do not stick. Control is a destination. The viewer is not there yet. The viewer is standing in their kitchen at 11 PM, looking at a balance that has not moved, doing math that does not make sense. The shame-to-relief script does not ask them to be a different person who has their money together. It asks them to look at the number, which is the only thing that has ever preceded relief. The minimum payment trap is real, the interest is real, and the months-until-payoff is a number that can be changed—not guaranteed, not fast, not easy, but visible . The brands winning finance UGC on TikTok are not the ones with the best dashboard or the most accurate categorization algorithm. They are the ones that understood the script’s first line must name the number the viewer is afraid to look at, and the final line must invite the viewer to say it out loud. The shame is the hook. The math is the proof. The download is the first look. The only job of the script is to make the viewer believe that looking at the number will not destroy them.